What Florida PIP Covers After a Car Accident in Miami
Most people in Miami learn what their Personal Injury Protection coverage does only after a crash, usually from an adjuster, and usually in pieces. I wanted the whole picture in one place, so I worked through the plain-language explanations published by a car accident attorney in Kendall (injurymiamilaw.com), whose site spends more space on PIP than on almost anything else, and then checked each piece against Florida’s no-fault statute. The pattern that came out of it is simpler than the insurance paperwork suggests, and it explains why so many claims go sideways.
PIP pays first, and the paper trail decides how much.
Two ledgers running at once
It helps to think of every Florida crash as opening two separate ledgers. One is your own PIP coverage, which pays regardless of who caused the accident. The other is any claim against the at-fault driver, which only opens up under certain conditions. Most confusion comes from mixing the two together or assuming the second one works like the first.
The no-fault ledger
Florida requires drivers to carry $10,000 in PIP coverage. After a crash, you claim against your own policy first, even if the other driver was entirely to blame. That is what no-fault means in practice, and it is why the firm’s site stresses that PIP often applies before anything else. This ledger is fast and limited. It covers a defined share of certain losses up to the policy limit, and it does not pay for pain and suffering at all.
The fault ledger
The second ledger is a bodily injury claim against the driver who caused the crash, or a claim under your own uninsured motorist coverage if that driver has too little insurance. Florida does not require most drivers to carry bodily injury liability coverage, so uninsured motorist coverage on your own policy often ends up doing the work people expect the other driver’s insurer to do.
To step outside the no-fault system and claim damages for pain and suffering, the injury generally has to meet a legal threshold, such as a permanent injury within a reasonable degree of medical probability or significant scarring. That threshold is where many serious cases are decided.
What the PIP ledger pays
Within the no-fault ledger, the numbers are fixed by statute, and they are smaller than many drivers assume when they sign up for the minimum policy.
Medical bills and lost income
PIP pays 80 percent of reasonable medical expenses and 60 percent of lost income, up to the $10,000 limit. It also includes a $5,000 death benefit. The remaining 20 percent of medical costs and 40 percent of lost wages are not covered by PIP, which is one reason a second ledger can matter so much after a serious crash. A $10,000 limit can disappear quickly. An emergency room visit with imaging, followed by a few weeks of therapy, can use up most of it before anyone has talked about lost wages.
The emergency medical condition rule
Access to the full $10,000 depends on a medical finding. If a qualified provider, such as a physician, dentist, physician assistant, or advanced practice registered nurse, determines that you had an emergency medical condition, the full medical benefit is available. Without that finding, medical benefits are capped at $2,500.
This single determination changes the value of the coverage by a factor of four, and many people never hear about it until the smaller cap is applied to their bills.
The clocks that start at the crash
The second part of the framework is timing. Several deadlines begin the moment the accident happens, and missing one can shrink or erase a claim no matter how clear the facts are.
The 14-day window
To use PIP benefits at all, you must get initial medical treatment within 14 days of the accident. Someone who feels sore but fine at the scene and waits to see if it passes can lose PIP coverage for injuries that show up later. This is the most common way people forfeit benefits without realizing it. A quick evaluation, even when the pain seems minor, keeps the coverage available.
The filing deadline
For most negligence claims arising from a car crash, Florida allows two years to file a lawsuit. That is shorter than it used to be, and older articles and forum posts that quote a longer period can mislead people. Evidence also fades well before any legal deadline, which is why investigating early tends to matter more than the deadline itself.
How shared fault changes the math
Florida uses a modified comparative negligence rule for most injury claims. If you are found partly at fault, your recovery on the fault ledger is reduced by your share of the blame, and if your share is more than half, you generally recover nothing from the other driver.
That rule makes early evidence about how the crash happened more important than many people expect. Photos of the scene, the police report, and the names of witnesses all feed directly into how fault gets divided later.
The paper trail decides the value
The third part of the framework is documentation, and it is where the firm’s published guidance is most specific. Its site says strong cases tend to come down to clear fault plus consistent medical documentation, and it lists the habits that weaken a claim.
Gaps in care
Insurers read a gap in treatment as evidence that an injury healed or was never serious. The firm’s site warns against gaps in care without documented reasons, and it notes that insurers routinely challenge treatment and work restrictions. If you have to pause treatment, having the reason written down, whether it was travel, cost, or a scheduling problem, helps close that argument before it starts.
Statements and exams
The site also flags two traps that catch people after a crash. One is downplaying symptoms or guessing in recorded statements to an adjuster. The other is the insurer-requested medical exam, which the site calls out as a source of avoidable PIP problems. Answering only what you know, and keeping bills and provider records organized, gives the insurer less room to deny what the records support.
Putting the framework to use
Once the two ledgers are clear, and you know which clocks are running, the questions after a crash get much easier to sort.
In the first days after a crash
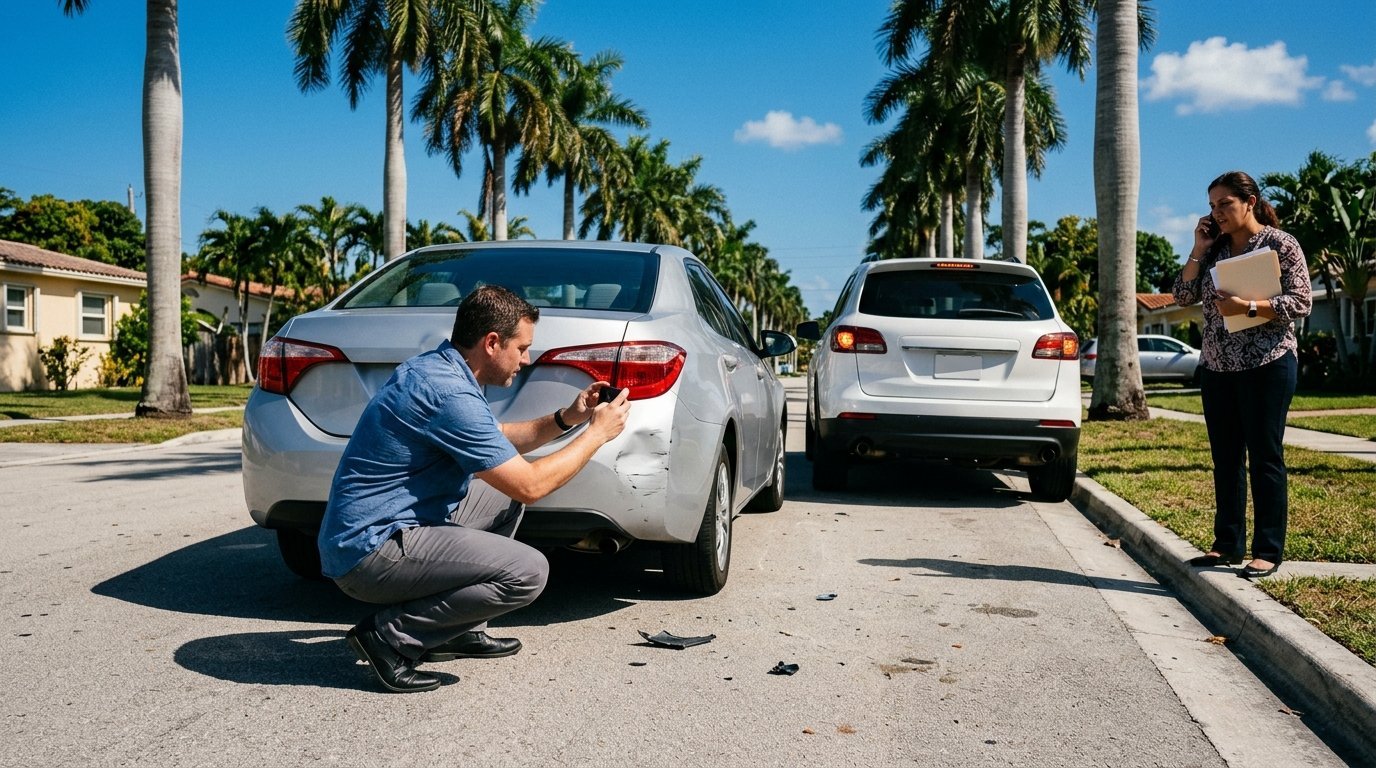
Get checked by a qualified provider within the 14-day window and ask whether the visit documents an emergency medical condition. Report the crash, photograph the scene if you can, and keep every bill and note from the start. Those steps protect the PIP ledger.
When the injury looks serious
If the injuries are significant or lasting, the fault ledger starts to matter, and so do coverage limits on both sides. The firm’s site notes that settlement value depends on how clear the fault is and how serious the injury is, along with treatment consistency and available coverage. It also warns that early low offers often ignore future care. That is usually when people talk to a lawyer, and many injury firms in Florida offer free consultations and work on contingency.
A final caution
This is general information and not legal advice, since every crash has details that change the answer. The framework is meant to help you ask better questions, whether you are talking to an adjuster, a doctor, or an attorney.